Some 73% of banking customers are only moderately satisfied, or less, with their primary bank, a new Celent report finds. While they’re not running for the door, this large “switchable middle,” may be tempted by a tech-savvy competitor’s more personalized offerings.
Winning and retaining customers demands end-to-end innovation. A modern core banking system empowers banks to deliver the personalized, AI-driven banking that customers expect, helping them retain more business over the long term.
Low attrition does not equal loyalty
Banks that mistake manageable attrition rates for customer loyalty may see business erode over time, as customers gradually move toward more personalized offers from competitors.
According to recent research conducted by Celent, 25% of customers admit they’ve recently considered switching their primary bank.
Banks recognize the need to modernize to retain customers, but their investment priorities don’t always reflect a willingness to act. While 46% are considering meaningful core modernization in 2027, only 20% rank such a move among their top three investment priorities, the report found.
That gap reflects an industrywide strategic misalignment: banks are funding the capabilities they want customers to see without always strengthening the foundations that these capabilities need to deliver value at scale.
Legacy foundations limit ambitions
Banks today are investing heavily in digital and AI, with 50% now ranking AI among their top strategic priorities, according to the Celent report. Yet the foundations on which AI depends do not always receive the same attention.
AI is only as effective as the data it can access. When customer and product data are fragmented across multiple systems, conflicting or unavailable in real time, AI lacks the trusted, complete view it needs to deliver value. Unfortunately, many banks do not prioritize the modernization required to create this trusted data foundation.
Modern core and data foundations turn AI ambition into value
To get the most out of AI, banks must modernize their core to ensure data is accessible, governed, and high quality. Simply put, banks cannot treat data modernization as a parallel workstream that will somehow connect back to an older core later. Core transformation and data modernization must move forward together.
Only when data can move seamlessly and securely across the organization can the institution build a complete view of customers, respond to their signals in real time and apply intelligence consistently. And only a modern and efficient core can support offers, advice, sharper risk decisions, stronger fraud detection, and faster product innovation that AI makes possible today. Without that foundation, big plans for AI fall into a patchwork of isolated pilots rather than a value-creating enterprise capability.
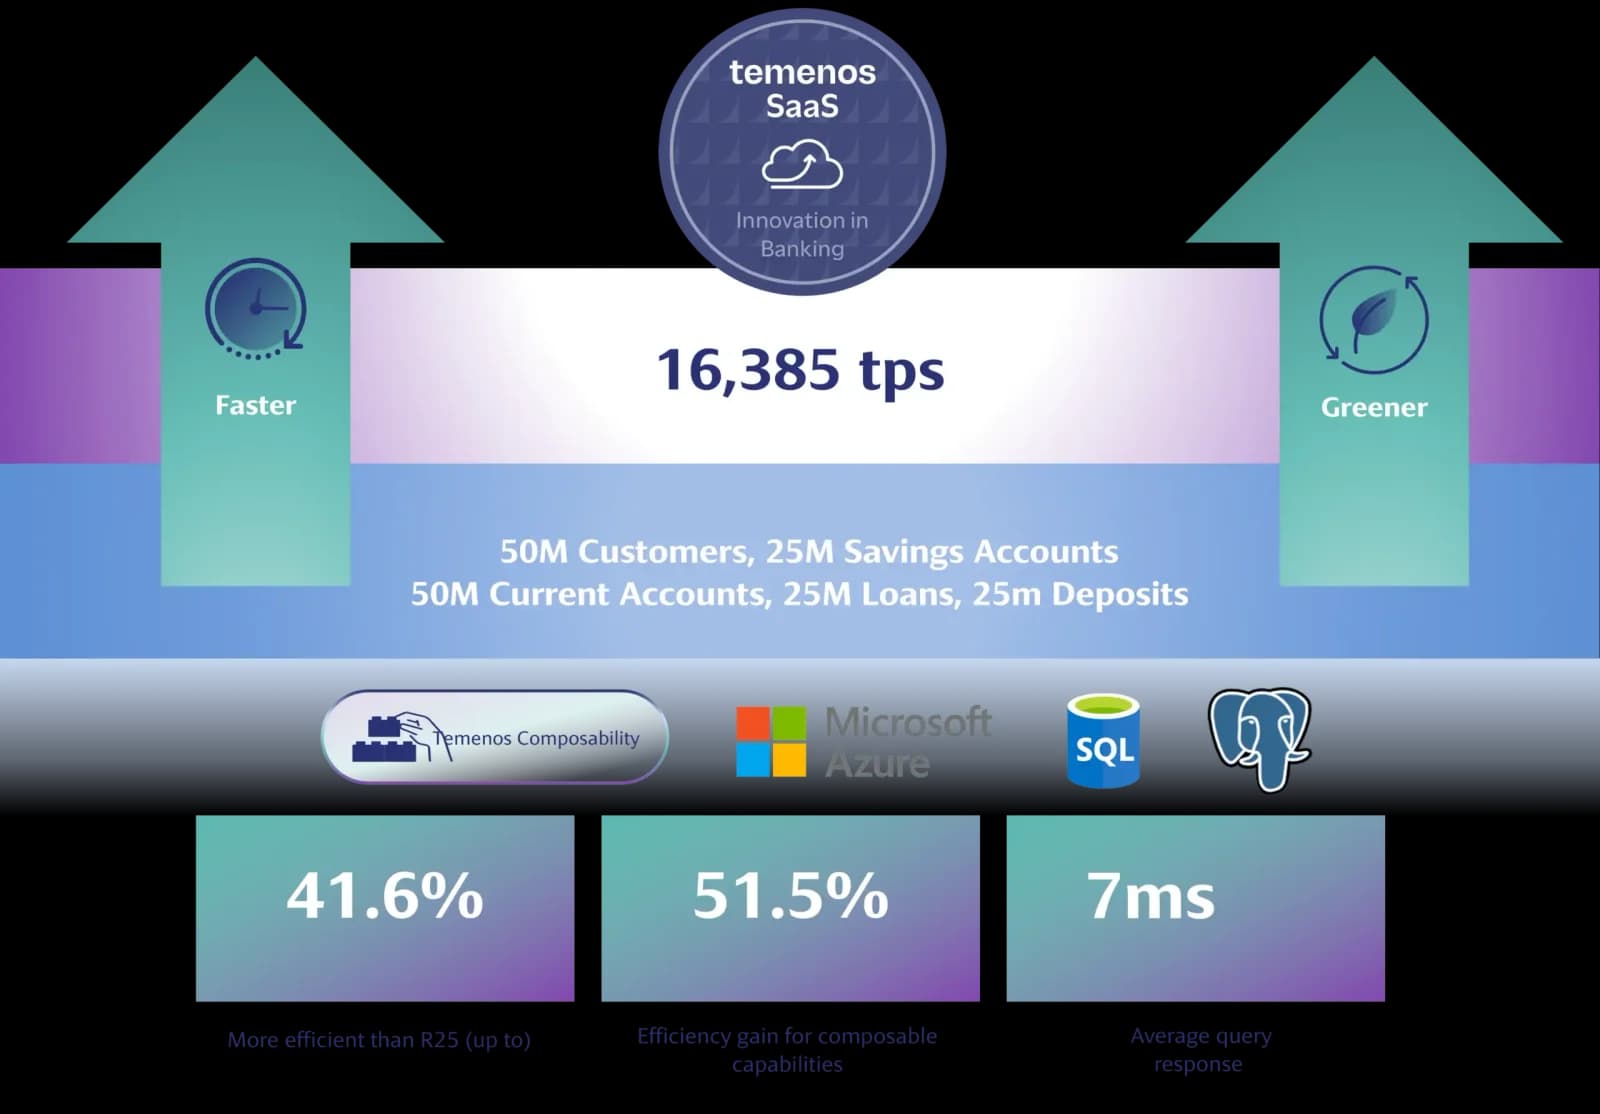
Many financial institutions, unfortunately, know this all too well: 27% of large banks cite current systems as a barrier to deploying AI. Foundational limitations slow personalization, payments innovation and new proposition launches, while pushing through changes becomes complex, costly and risky. Modern core foundations reduce those dependencies while supporting the resilience and processing integrity banks cannot compromise.
What banks need to consider
For core modernization to be successful, banks should ask three questions:
- Where are legacy platforms constraining innovation, personalization, risk management, or customer insight?
- If AI is a strategic priority, are core and data foundations ready to support it at scale?
- Is the bank treating core modernization as a business-critical enabler of future banking, or as a lower-priority infrastructure project?
Core modernization should not compete with digital and AI investment. It is what makes those investments work, giving banks the data, flexibility, and resilience to deliver more intelligent, personalized services at speed.